
Get smart everyday buys delivered free — and shop member deals
- Fast, free delivery on millions of items
- Access to Prime Big Deal Days deals on October 6–7
- Prime Video, Amazon Music and more included
At a Glance
| Criteria | Online High-Yield Savings Account | Traditional Bank Savings Account | Winner |
|---|---|---|---|
| Interest Rate | Typically 4.00% – 4.50% | Around 0.01% – 0.10% | A |
| Fees | Usually none or minimal | May include monthly maintenance fees | B |
| Accessibility | Limited to online or mobile access | Physical branches, ATMs available | A |
| Account Features | Basic savings features, often no ATM card | Standard savings account features, ATM access | B |
| Security | FDIC insured, similar security standards | FDIC insured, similar security standards | A |
| Customer Service | Primarily digital customer support | In-person and phone support | B |
| Minimum Balance | Often no minimum or low minimum | Varies, often higher minimums | A |
| Ease of Use | Designed for digital use, streamlined interface | Available in branch, more familiar interface | A |
The High-Yield Cash Guide (2026 Edition): How to Choose the Best Savings Accounts and CDs to Earn More on Your Cash
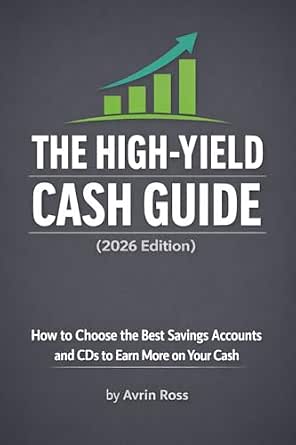
<p>This guide stands out for its up-to-date strategies tailored for 2026, helping readers navigate the latest high-yield savings options and CDs. Compared with other resources, it emphasizes maximizing returns through informed decision-making rather than listing specific account features. However, its lack of detailed specifications or user reviews limits its practical application for those seeking concrete product comparisons. It’s ideal for readers who want strategic insights but not detailed product breakdowns.</p>
The High-Yield Cash Guide (2026 Edition): How to Choose the Best Savings Accounts and CDs to Earn More on Your Cash
- ✔ Edition: 2026
- ✔ Focus: Savings strategies
- ✔ Format: Guidebook

What Your Bank Doesn’t Tell You: How to Use High-Yield Savings Accounts, Roth IRAs, 401(k)s, HSAs, and Other Smart Accounts to Bu…
- ✔ Author: Unknown
- ✔ Focus: Long-term wealth
- ✔ Content Type: Financial strategies
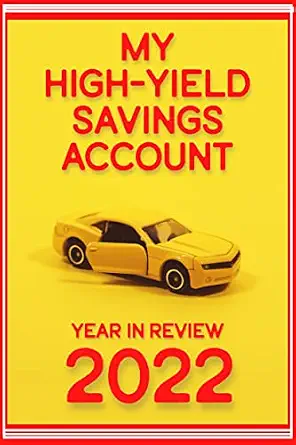
My High-Yield Savings Account: Year in Review 2022 (Great Investing Book 106)
- ✔ Year Reviewed: 2022
- ✔ Focus: Market trends and analysis
- ✔ Content Type: Year-in-review
Pros:
- Provides updated strategies for 2026
- Focuses on maximizing savings with high-yield options
- Helps readers develop personalized savings strategies
Cons:
- No detailed specifications provided
- Lacks user reviews or ratings
- Limited practical product comparisons
Best for: Savvy savers seeking strategic guidance for maximizing high-yield returns in 2026.
Not ideal for: Beginners or those wanting detailed account features or user reviews.
Bottom line: A strategic resource best suited for those wanting to optimize their savings approach in 2026.
“A strategic resource best suited for those wanting to optimize their savings approach in 2026.”
What Your Bank Doesn’t Tell You: How to Use High-Yield Savings Accounts, Roth IRAs, 401(k)s, HSAs, and Other Smart Accounts to Bu…
<p>This book offers an in-depth look at leveraging a variety of financial accounts—including high-yield savings—to build wealth over time. Compared with more narrowly focused guides, it provides broader strategies that integrate savings with retirement and health accounts, making it suitable for those aiming for comprehensive financial planning. However, the content can be complex for beginners, and it lacks specific product features or reviews. It’s best suited for readers ready to think long-term and diversify their financial tools.</p>
Pros:
- Provides comprehensive financial strategies
- Focuses on building long-term wealth
- Covers multiple smart financial accounts
Cons:
- No specific price information
- No customer ratings available
- Content may be complex for beginners
Best for: Long-term investors and savers looking to integrate high-yield accounts into broader wealth strategies.
Not ideal for: Beginners or those seeking quick, straightforward savings solutions.
Bottom line: A comprehensive guide for those wanting to incorporate high-yield savings into broader wealth-building plans.
“A comprehensive guide for those wanting to incorporate high-yield savings into broader wealth-building plans.”
My High-Yield Savings Account: Year in Review 2022 (Great Investing Book 106)
<p>This book reviews high-yield savings accounts and investment strategies from 2022, offering insights into market trends and how they impact savings. Compared to the other options, it provides historical analysis rather than current account specifics, making it less practical for choosing a savings account today. Nevertheless, it’s valuable for investors interested in understanding how market shifts influence savings yields. Its lack of detailed product features or reviews makes it less suitable for immediate account selection but useful for contextual understanding.</p>
Pros:
- Provides detailed insights into 2022 savings accounts
- Includes year-in-review market analysis
- Suitable for understanding market influence on yields
Cons:
- No detailed product features or specifications
- No customer reviews available
- Limited practical guidance for current accounts
Best for: Investors and savers interested in market trends and historical performance analysis.
Not ideal for: Those seeking current account details or practical savings tools.
Bottom line: A useful resource for understanding market influence on savings, but less practical for immediate account comparisons.
“A useful resource for understanding market influence on savings, but less practical for immediate account comparisons.”
As an Amazon Associate we earn from qualifying purchases.
Key Differences
The core distinction lies in the interest rates offered. Online high-yield savings accounts can provide interest rates four to five times higher than traditional banks, which translates into faster savings growth over time. This makes online accounts particularly attractive for long-term savers or those aiming to maximize earnings without additional risk. However, this benefit comes with less physical access. Traditional banks provide immediate in-person service, cash deposits, and face-to-face support, which can be invaluable for certain users. They also tend to have higher minimum deposit requirements and may charge fees, reducing overall returns. For savers prioritizing maximum earnings and comfortable with digital banking, online accounts provide clear value. Conversely, those who need physical branches, ATM access for cash needs, or personal customer service may find traditional banks more suitable, despite the lower interest rates. The decision ultimately depends on whether the priority is higher interest or in-person convenience.Detailed Comparison
Interest Rate (Online High-Yield Savings Account wins — major)
Interest rate differences are substantial and decisive. Online high-yield accounts offer rates around 4.00%-4.50%, compared to traditional savings accounts offering roughly 0.01%-0.10%. This gap means that online accounts can generate significantly more interest, especially over years, boosting long-term savings. For example, earning 4.50% instead of 0.10% on $10,000 results in over $400 extra annually, making the online option a clear winner for maximizing growth.
Fees (Online High-Yield Savings Account wins — moderate)
Fee structures favor online high-yield accounts, which typically waive monthly fees and ATM charges, whereas traditional banks may impose monthly maintenance and withdrawal fees. For cost-conscious savers, this difference can add up, making online accounts more economical and increasing net interest gains. The fee advantage is moderate but meaningful when comparing total savings returns.
Accessibility (Traditional Bank Savings Account wins — moderate)
Physical branch access favors traditional banks, which allow in-person deposits, withdrawals, and face-to-face support. Online accounts restrict users to digital channels, which may be less convenient for cash handling or urgent needs. For those valuing in-person interactions, traditional banks are preferable. For digital natives or those comfortable online, the accessibility difference is minor.
Account Features (Traditional Bank Savings Account wins — minor)
Traditional banks often provide ATM cards, check-writing, and in-branch services, offering more flexible account features. Online high-yield accounts typically focus on basic savings functions, with limited or no ATM access. Users needing these features should lean toward traditional banks; others focused solely on earning interest can opt for online accounts.
Security (minor difference)
Both options are FDIC insured, offering similar deposit security. There is no significant difference in safety, making this criterion neutral in choosing between the two.
Customer Service (Traditional Bank Savings Account wins — moderate)
Traditional banks offer in-person and phone support, which can be advantageous for complex issues or personal reassurance. Online banks primarily rely on digital support channels, which can be efficient but less personal. Choose traditional if in-person or immediate support is critical; online accounts suit those comfortable with digital communication.
Minimum Balance (Online High-Yield Savings Account wins — major)
Online high-yield savings accounts often feature low or no minimum balance requirements, making them accessible to most users. Traditional banks may impose higher minimums, which could require maintaining larger balances to avoid fees. For those with smaller savings, online options are more inclusive.
Ease of Use (Online High-Yield Savings Account wins — minor)
Online accounts tend to have user-friendly apps and websites designed for quick and straightforward management. Traditional banks, especially those with physical branches, may have less streamlined digital interfaces, though they are familiar to many users. For digital-savvy savers, online accounts offer a better experience.
Online High-Yield Savings Account: Pros and Cons
Pros:
- Higher interest rates significantly accelerate savings growth
- Low or no fees increase net returns
- Low minimum balance requirements improve accessibility
- Streamlined digital management is convenient for tech-savvy users
Cons:
- Lack of physical branches limits in-person deposits and support
- Limited account features like ATM access or check-writing
- Possible concerns over digital security for some users
Traditional Bank Savings Account: Pros and Cons
Pros:
- Access to physical branches and ATMs for cash and in-person service
- More comprehensive account features, including ATM cards and check-writing
- Familiar environment and face-to-face customer support
Cons:
- Much lower interest rates reduce savings growth
- Higher fees and minimum balance requirements can diminish returns
- Less streamlined digital experience compared to online-only options
Who Should Choose What
Choose Online High-Yield Savings Account if:
- You prioritize maximizing interest earnings over in-person service
- You are comfortable managing your finances digitally
- You want low fees and low minimum balance requirements
- You are primarily saving long-term and don’t need cash deposits frequently
Choose Traditional Bank Savings Account if:
- You value in-person support and physical branch access
- You need ATM access for cash withdrawals or deposits
- You prefer comprehensive account features like check-writing
- You are less comfortable with digital-only banking or need face-to-face assistance
Skip both if: You are not interested in high-yield accounts and prefer traditional savings options or alternative investments
Value for Money
Paying more for an online high-yield savings account makes sense for most savers focused on growth, especially if they have larger balances or long-term goals. The higher interest rates offer better value over time, often outweighing the convenience of physical branches. For users who prioritize in-person service or need cash handling, the lower rates of traditional banks are less attractive, unless they also value the additional features and support.Overall, high-yield online savings accounts represent better value for those comfortable with digital banking and seeking maximum interest, whereas traditional banks may serve niche needs where accessibility and personal support outweigh earning potential.Final Verdict
For most savers aiming to grow their funds efficiently, online high-yield savings accounts are the clear choice due to their superior interest rates and lower fees. They suit users comfortable with digital banking, long-term savers, and those with smaller initial deposits. Traditional bank savings accounts remain suitable for individuals who prefer in-person service, need cash deposits, or require features like check-writing and ATM access. The biggest deciding factor is whether maximizing interest or in-person convenience matters more. Overall, if your priority is earning the highest possible interest and managing your savings online, choose Option A. If you value physical access and face-to-face service, consider Option B.
Frequently Asked Questions
Are online high-yield savings accounts safe?
Yes. They are FDIC insured up to applicable limits, just like traditional bank savings accounts, ensuring your deposits are protected.
Can I access my online high-yield savings account with an ATM?
Most online high-yield savings accounts do not provide ATM cards, limiting direct cash access. You can typically transfer funds to a linked checking account for ATM withdrawals.
Do online high-yield savings accounts have fees?
Many online accounts waive monthly maintenance and ATM fees, but it’s important to verify specific account terms before opening.
How long does it take to transfer money between accounts?
Transfers from online high-yield accounts to linked checking accounts are usually completed within one to three business days, depending on the bank.
Is it better to have multiple savings accounts or one high-yield account?
Multiple accounts can help allocate funds for different goals, but a single high-yield account generally maximizes interest. Choose based on your savings strategy.
Fall Picks
fall essentials
As an affiliate, we earn on qualifying purchases.